
Original graphic: URA site context map, adapted for this analysis.
The New Upper Changi Road GLS tender has produced one of the clearest signals yet that developers remain willing to pay up for a well-located suburban site. A joint venture involving UOL Group, Singapore Land and CapitaLand Development submitted the top bid of S$1.425 billion, or S$1,537.05 psf per plot ratio (psf ppr), for the 30,769 sq m parcel.
That number matters because it is not simply another land-sale result. It establishes a new benchmark for a pure-residential site in Singapore’s Outside Central Region (OCR), while also setting the cost base for a future project of approximately 1,010 homes. The key question for buyers is therefore not whether Bedok is attractive—it plainly is—but whether the eventual launch price will fairly reflect the location and the risks of buying into a large, high-cost development.
What the GLS result tells us
URA released the site under the 1H2026 Government Land Sales Programme. The parcel is bounded by New Upper Changi Road and Bedok South Road and includes the former Temasek Primary and Secondary School grounds. It has a maximum gross floor area of 86,154 sq m and a 99-year leasehold tenure.
The winning bid was substantially ahead of the competition. CDL and Hong Realty submitted S$1,350.08 psf ppr, while the GuocoLand, Hong Leong Holdings and Mitsui Fudosan consortium bid S$1,340.01 psf ppr. Sim Lian bid S$1,310.18 psf ppr. The top offer was therefore 13.8 per cent above the next bid and 15.6 per cent above Allgreen Properties’ nearby Bedok Rise land rate of S$1,330 psf ppr.
Analysts cited by The Business Times expect future selling prices to start above S$3,000 psf, with an average potentially around S$3,100 to S$3,200 psf. These are estimates, not an announced price list. Actual pricing will depend on unit sizes, views, floor levels, tenure assumptions, construction costs, financing conditions and buyer response.
Why Bedok gives the project a strong foundation
Bedok is a mature, populous eastern town rather than a speculative new precinct. The planning area has approximately 274,360 residents and offers the everyday infrastructure that families normally have to wait years for in a new township: established schools, markets, shops, food options, healthcare, recreation and multiple transport routes.
The development should also benefit from an unusually deep potential upgrader pool. Nearly 2,300 HDB flats in the area reached their minimum occupation period between 2022 and 2026. Newer four-room and five-room flats recorded 2025 median resale prices of about S$860,000 and S$1.03 million respectively. Some owners may have meaningful proceeds to redeploy, although affordability still depends on outstanding loans, CPF refunds, taxes, the replacement-home budget and prevailing mortgage rates.
For investors, the eastern employment story is equally important. Changi Airport and Changi Business Park create a tenant base beyond the immediate neighbourhood. The possible future role of Tanah Merah MRT as an interchange with the Thomson-East Coast Line could add connectivity and rental interest, but buyers should treat that as a future possibility rather than guaranteed immediate value.
GLS advantages in point form
- Mature Bedok catchment: Buyers get established amenities and services instead of relying entirely on future plans.
- Strong own-stay appeal: The combination of schools, food, retail and East Coast Park can support practical family living.
- Large upgrader base: Recent MOP completions may support demand for two- to four-bedroom homes.
- Recognised developer consortium: UOL, Singapore Land and CapitaLand bring substantial development experience and marketing reach.
- Employment-node access: Changi Airport and Changi Business Park may support rental demand from workers and professionals.
- Potential lifestyle premium: East Coast Park and the broader eastern identity can attract buyers who value recreation and coastal proximity.
- Broad unit mix: Two- to four-bedroom formats could keep total price quantum more accessible than an exclusively luxury project.
- Benchmark-setting confidence: The aggressive bid suggests the consortium sees long-term value in Bedok’s location and catchment.
GLS disadvantages in point form
- Very high land cost: S$1,537.05 psf ppr leaves little room for pricing mistakes.
- Likely expensive launch: A projected S$3,100–S$3,200 psf average would place the project well above many older eastern comparables.
- Large-project competition: Approximately 1,010 homes means a lengthy sales programme and substantial internal density.
- Pipeline risk: Four Bedok-area GLS sites could add about 3,185 private homes between 2025 and 2028, potentially slowing absorption.
- Site preparation obligations: The successful bidder must bear demolition costs and asbestos-survey obligations.
- Future benefits are uncertain: Planned transport improvements may take time and may not translate into immediate resale gains.
- Limited margin for resale upside: Buying at an aggressive launch price can reduce the buffer if prices flatten.
- Potential congestion: More residents may increase pressure on roads, schools, stations and existing amenities.
How it compares with nearby eastern launches
Parktown Residence in Tampines is the clearest scale comparison. It has 1,193 units and is directly connected to Tampines North MRT. A search result from April 2026 reported 1,160 units sold and 33 available, although live balance-unit figures can change and should be verified through official channels. Parktown demonstrates that a large, well-connected suburban project can achieve strong take-up, but its Tampines North positioning and earlier pricing are not directly interchangeable with a future Bedok launch.
Vela Bay at Bayshore is a smaller east-side alternative of approximately 515 units across two towers, with one- to five-bedroom formats and direct Bayshore MRT access. The project shares the lifestyle and transport qualities that may appeal to New Upper Changi buyers, but it offers a more intimate scale and a stronger immediate waterfront identity. The Business Times cited a year-to-date median of S$2,863 psf for Vela Bay. Balance-unit charts are indicative only; buyers should check current availability before making comparisons.
Sceneca Residence at Tanah Merah is another useful benchmark. The 268-unit mixed-use project sits beside Tanah Merah MRT and offers one- to four-bedroom homes. It achieved an average launch-weekend price of S$2,072 psf in January 2023, while its year-to-date sub-sale median was reported at S$2,312 psf. Developer units were reported as fully sold in a 2026 search result, so any remaining opportunities may be resale or sub-sale units rather than fresh developer inventory.
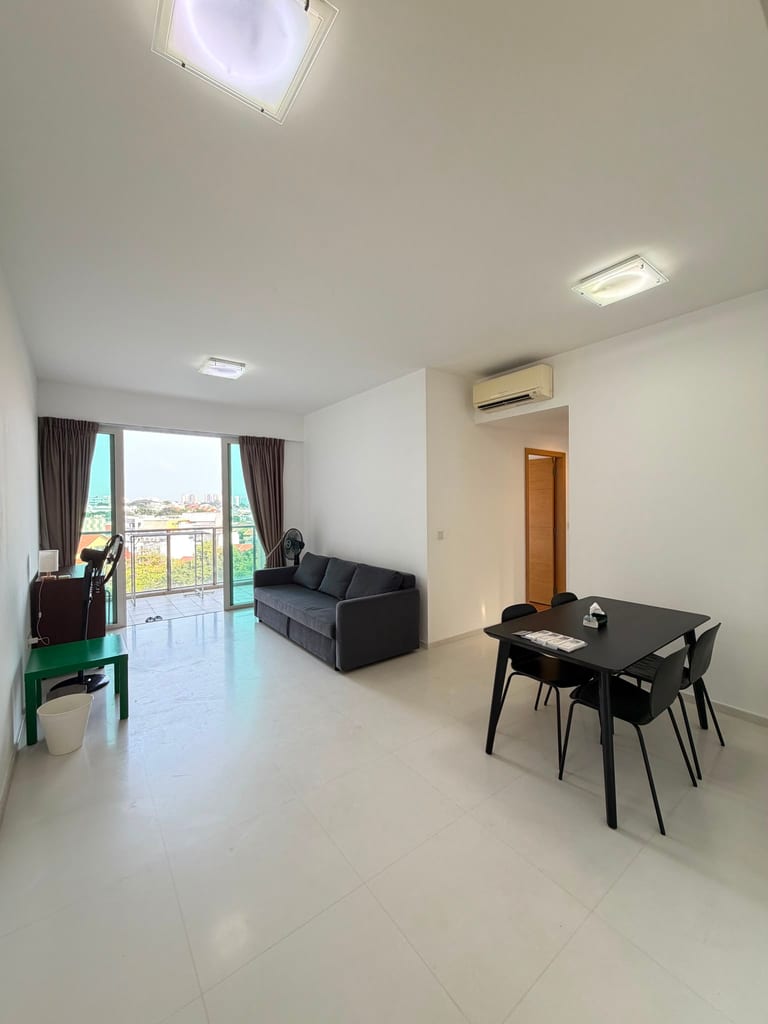
For a live east-side reference, Sebastian’s Vacanza @ East three-bedroom rental listing illustrates the practical appeal of established eastern housing: a 1,012 sq ft furnished home with three bedrooms and two bathrooms. It is not a direct price comparison with a new launch, but it helps frame the trade-off between immediate usable space and paying a premium for brand-new facilities.
The existing Thomson Reserve listing is a less geographically direct but useful comparison of another large UOL, Singapore Land and CapitaLand-linked project. Its proposed 1,268-unit scale and two- to five-bedroom range show how buyers may compare future launches by developer, unit mix, connectivity and facilities—not merely by district label.
Why I Will Buy
I would consider buying the New Upper Changi Road project if my priority were long-term own-stay value and I could comfortably afford the launch pricing. Bedok has the rare combination of a mature town, established demand, eastern lifestyle appeal and access to employment nodes. That is a more defensible foundation than buying solely on an untested future transformation story.
I would also value the consortium’s ability to plan and execute a large development. A 1,010-unit project can provide a broad range of layouts and facilities, which may suit families at different life stages. If the final design creates good separation from roads, sensible traffic circulation, attractive communal spaces and efficient floor plans, the project could become a major new residential anchor for the neighbourhood.
However, I would buy only after comparing actual stacks, facing, maintenance fees, unit efficiency and total quantum against Vela Bay, Sceneca resale opportunities, Bedok resale homes and other upcoming launches. Location alone does not justify any price.
Why I Will Not Buy
I would not buy if the launch prices move too far ahead of comparable eastern transactions. A premium can be justified for new construction, developer quality and a superior site, but it still needs to leave room for ownership costs and future market cycles. At S$3,100–S$3,200 psf, even a modestly sized family unit could require a very large cash and financing commitment.
I would also hesitate if several nearby projects launch or sell units at the same time. The projected 3,185-home pipeline creates real absorption risk. Strong initial sales at one project do not guarantee that every buyer will have pricing power later, especially when multiple developments compete for the same upgrader and investor pool.
Finally, I would not pay today for transport improvements that remain in the future. A prudent buyer should assess current travel times, current amenities and current rental evidence first, then treat future infrastructure as upside rather than as the central reason to purchase.
Bottom line
The New Upper Changi Road GLS site is compelling because it combines a mature Bedok location with a strong developer consortium and a sizeable demand base. It is risky because the consortium paid a record-setting suburban land rate, making a premium launch almost unavoidable. My view is straightforward: buy for the established neighbourhood and long-term usability, not for a speculative quick profit—and walk away if the price erases the value of those advantages.
Availability and pricing for comparison projects are indicative and dynamic. Always verify the latest balance units, transaction evidence, financing costs and official sales information before committing.
Disclaimer
This information is provided solely on a goodwill basis, and does not relieve parties of their responsibility to verify the information from the relevant sources and/or seek appropriate advice from relevant professionals, such as valuers, financial advisors, bankers and lawyers. For avoidance of doubt, PropNex Realty Pte Ltd, and its salesperson, accepts no responsibility for the accuracy, reliability, and/or completeness of the information provided. Copyright in this publication is owned by Sebastian Teo, and this publication may not be reproduce or transmitted in any form, or by any means in whole, or in part, without prior written approval.